
Did you know that nearly 40% of Americans feel confused by the fine print in their financial contracts? Navigating the world of protection can feel like learning a foreign language. Before you compare quotes or decide on a coverage amount, you must master the essential vocabulary used by providers.
A standard agreement typically involves an insurer, the person who owns the contract, and the individual being covered. You will also encounter concepts like beneficiaries, monthly premiums, and the final death benefit payout. Understanding these basics is the best way to ensure your family stays protected.
Keep in mind that this guide focuses on common U.S. definitions. Specific requirements, fees, and legal language often vary by state and individual company guidelines. Always review your documents carefully to make the smartest choice for your future.
Key Takeaways
- Learn the core vocabulary before comparing different financial products.
- Identify the roles of the insurer, owner, and the person covered.
- Understand how premiums and death benefits impact your overall budget.
- Recognize that state laws influence how these agreements function.
- Always verify specific details directly with your chosen provider.
Life Insurance Policy Terms That Define Basic Coverage
Navigating the world of life insurance starts with grasping the core definitions that shape your protection. Understanding these concepts ensures that your insurance policy coverage aligns perfectly with your long-term financial goals.
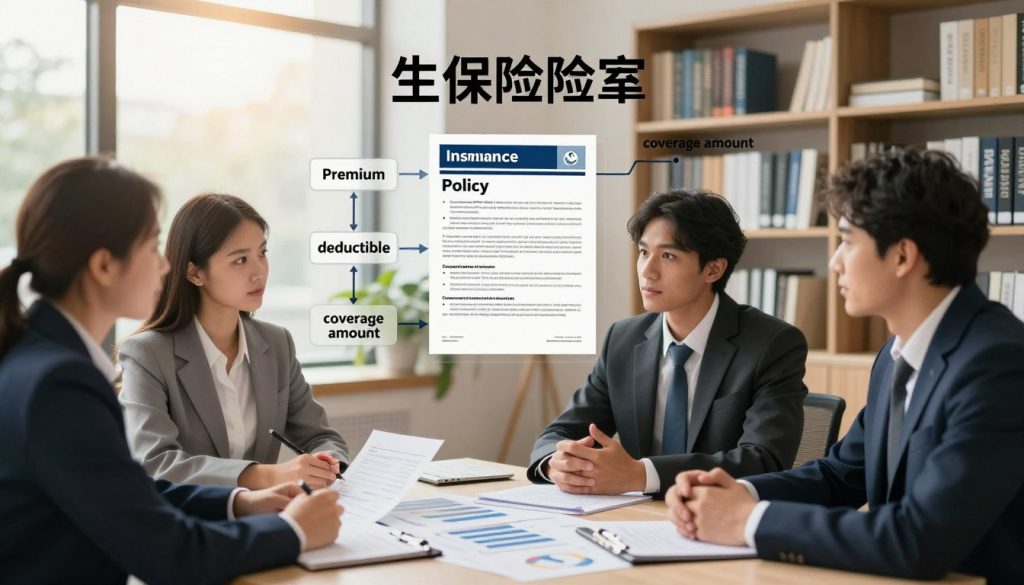
Policyholder, Insured Person, and Insurance Company
A life insurance contract involves three primary parties. The insurance company is the entity that issues the policy and promises to pay the benefit. The policyholder is the individual who owns the contract and is responsible for paying the premiums.
The insured person is the individual whose life is covered by the policy. While the policyholder and the insured are often the same person, they can be different. For example, a business might own a policy on a key executive, or a parent might own a policy on a child.
Death Benefit and Insurance Policy Coverage
The death benefit is the core promise of your agreement. It represents the specific amount of money the insurer pays to your chosen recipients after the insured person passes away.
This payout is subject to the specific terms and exclusions outlined in your contract. Maintaining consistent insurance policy coverage is vital to ensure that this benefit remains active when your loved ones need it most.
Beneficiaries and How Benefit Proceeds Are Paid
Beneficiaries are the people or entities you designate to receive the death benefit. You can name individuals, such as a spouse or children, or even a trust or charity.
When a claim is filed, the insurance company reviews the documentation before releasing the funds. Proceeds are typically paid out as a lump sum, though some policies offer options for installment payments over time.
Term Life and Permanent Life Insurance
Choosing between different types of protection is a major decision. Term life insurance provides coverage for a set period, such as 10, 20, or 30 years. It is often the most affordable way to secure a large death benefit.
In contrast, permanent life insurance is designed to stay in force for your entire life, provided premiums are paid. These policies often include a cash value component that can grow over time, offering a unique blend of protection and savings.
| Feature | Term Life | Permanent Life |
|---|---|---|
| Duration | Fixed period | Lifetime |
| Cash Value | None | Accumulates |
| Cost | Lower premiums | Higher premiums |
| Primary Goal | Temporary protection | Long-term security |
Premiums, Policy Costs, and Insurance Terms and Conditions
Managing your life insurance requires a clear grasp of how costs and contractual obligations function over time. Understanding these core components helps you maintain your coverage and ensures your beneficiaries are protected when it matters most.
Insurance Premium Payments and Payment Schedules
When you purchase a policy, you agree to a specific schedule for insurance premium payments. Most insurers offer flexibility, allowing you to pay monthly, quarterly, semiannually, or annually.
Choosing an annual payment schedule can sometimes result in a small discount, as it reduces administrative processing for the company. Regardless of the frequency, staying consistent with these payments is the primary way to keep your coverage active.
| Payment Frequency | Administrative Effort | Potential Savings |
|---|---|---|
| Monthly | High | None |
| Quarterly | Medium | Low |
| Annually | Low | High |
Cash Value, Account Growth, and Cost of Insurance
Permanent life insurance policies often include a cash value component that grows over time. This growth is influenced by the cost of insurance, which covers the insurer’s risk, and various administrative charges deducted from your account.
It is important to remember that actual account growth may differ from the initial illustrations provided during the sales process. Market performance and internal policy expenses can impact the final value, so you should review your annual statements carefully.
Grace Periods, Lapsed Policies, and Reinstatement
Life happens, and sometimes a payment might be missed. Most contracts include a grace period, typically 30 or 31 days, which allows you to pay the overdue premium without losing your coverage.
If you fail to pay within this window, your policy may lapse. While some companies allow for reinstatement, this process often requires proof of insurability and the payment of all back premiums plus interest.
Policy Exclusions and Contestability Rules
Every contract contains specific insurance terms and conditions that define the scope of your protection. One critical aspect is the contestability period, which usually lasts for the first two years of the policy.
During this time, the insurer may investigate the accuracy of the information provided on your application. Additionally, policy exclusions—such as specific high-risk activities or suicide clauses—limit the circumstances under which a death benefit is paid. Always read your contract thoroughly to understand these limitations.
Life Insurance Benefits, Riders, and Policy Changes
Beyond the standard death benefit, your policy can offer flexible tools to protect your financial future. These life insurance benefits allow you to customize your coverage to match your specific lifestyle and health needs. By choosing the right additions, you gain peace of mind knowing your plan adapts as your circumstances change.
Common Policy Riders for Additional Protection
Adding policy riders is a popular way to expand your coverage without buying an entirely new contract. These optional provisions provide extra layers of security for you and your loved ones.
Accelerated Death Benefit Rider
This rider allows you to access a portion of your death benefit while you are still living if you are diagnosed with a terminal illness. It provides crucial financial support during a very difficult time, helping to cover medical bills or other urgent expenses.
Waiver of Premium Rider
If you become totally disabled and cannot work, this rider ensures your policy stays active. The insurance company will pay your premiums for you, so you do not have to worry about losing your coverage when you need it most.
Child, Spouse, and Long-Term Care Riders
You can also extend protection to your family members or prepare for future health needs. These riders offer a cost-effective way to secure coverage for your spouse or children under one primary policy. Long-term care riders are particularly helpful for covering the high costs of assisted living or nursing home care later in life.
Loans, Withdrawals, and Their Effect on Benefits
Permanent life insurance policies often build cash value over time. You may choose to borrow against this value or make a withdrawal to handle unexpected costs. However, it is important to understand that these actions can reduce your total death benefit.
- Unpaid loans will be deducted from the final payout to your beneficiaries.
- Withdrawals may permanently lower the cash value growth of your policy.
- If a loan balance grows too large, it could potentially cause your policy to lapse if not managed correctly.
Policy Surrender Options and Surrender Charges
If you decide you no longer need your coverage, you have policy surrender options available. You can choose to cancel the policy and receive the remaining cash value, minus any applicable fees. Be aware that many contracts include surrender charges during the first several years, which can significantly reduce the amount you receive back.
Insurance Policy Maturity and What Happens at the End of the Term
Understanding insurance policy maturity is vital for long-term planning. A permanent policy typically matures when you reach a certain age, such as 100 or 121, at which point the cash value may equal the death benefit. In contrast, a term policy simply ends when the contract period expires.
Most term policies do not provide a maturity payout unless the contract specifically includes a return-of-premium feature. It is essential to review your specific contract to see if you have options to renew or convert your term policy into a permanent one before the term ends.
Conclusion
Mastering life insurance policy terms empowers you to make informed decisions for your family. You gain the ability to compare premiums, coverage amounts, and specific riders with confidence. This knowledge ensures your plan aligns perfectly with your long-term financial goals.
Your ideal coverage depends on your unique health history, current budget, and personal responsibilities. Reviewing the policy illustration and the full contract helps you understand the specific guarantees provided by carriers like Northwestern Mutual or New York Life. These documents clarify how your money works and what benefits your loved ones receive.
Take the time to evaluate every detail before you sign any paperwork. Reach out to a qualified insurance professional to discuss your specific needs and clarify any complex life insurance policy terms. A clear understanding of these details protects your assets and provides peace of mind for years to come.
What questions do you have about your current coverage? Share your thoughts or reach out to a licensed agent to start your journey toward better financial security today.